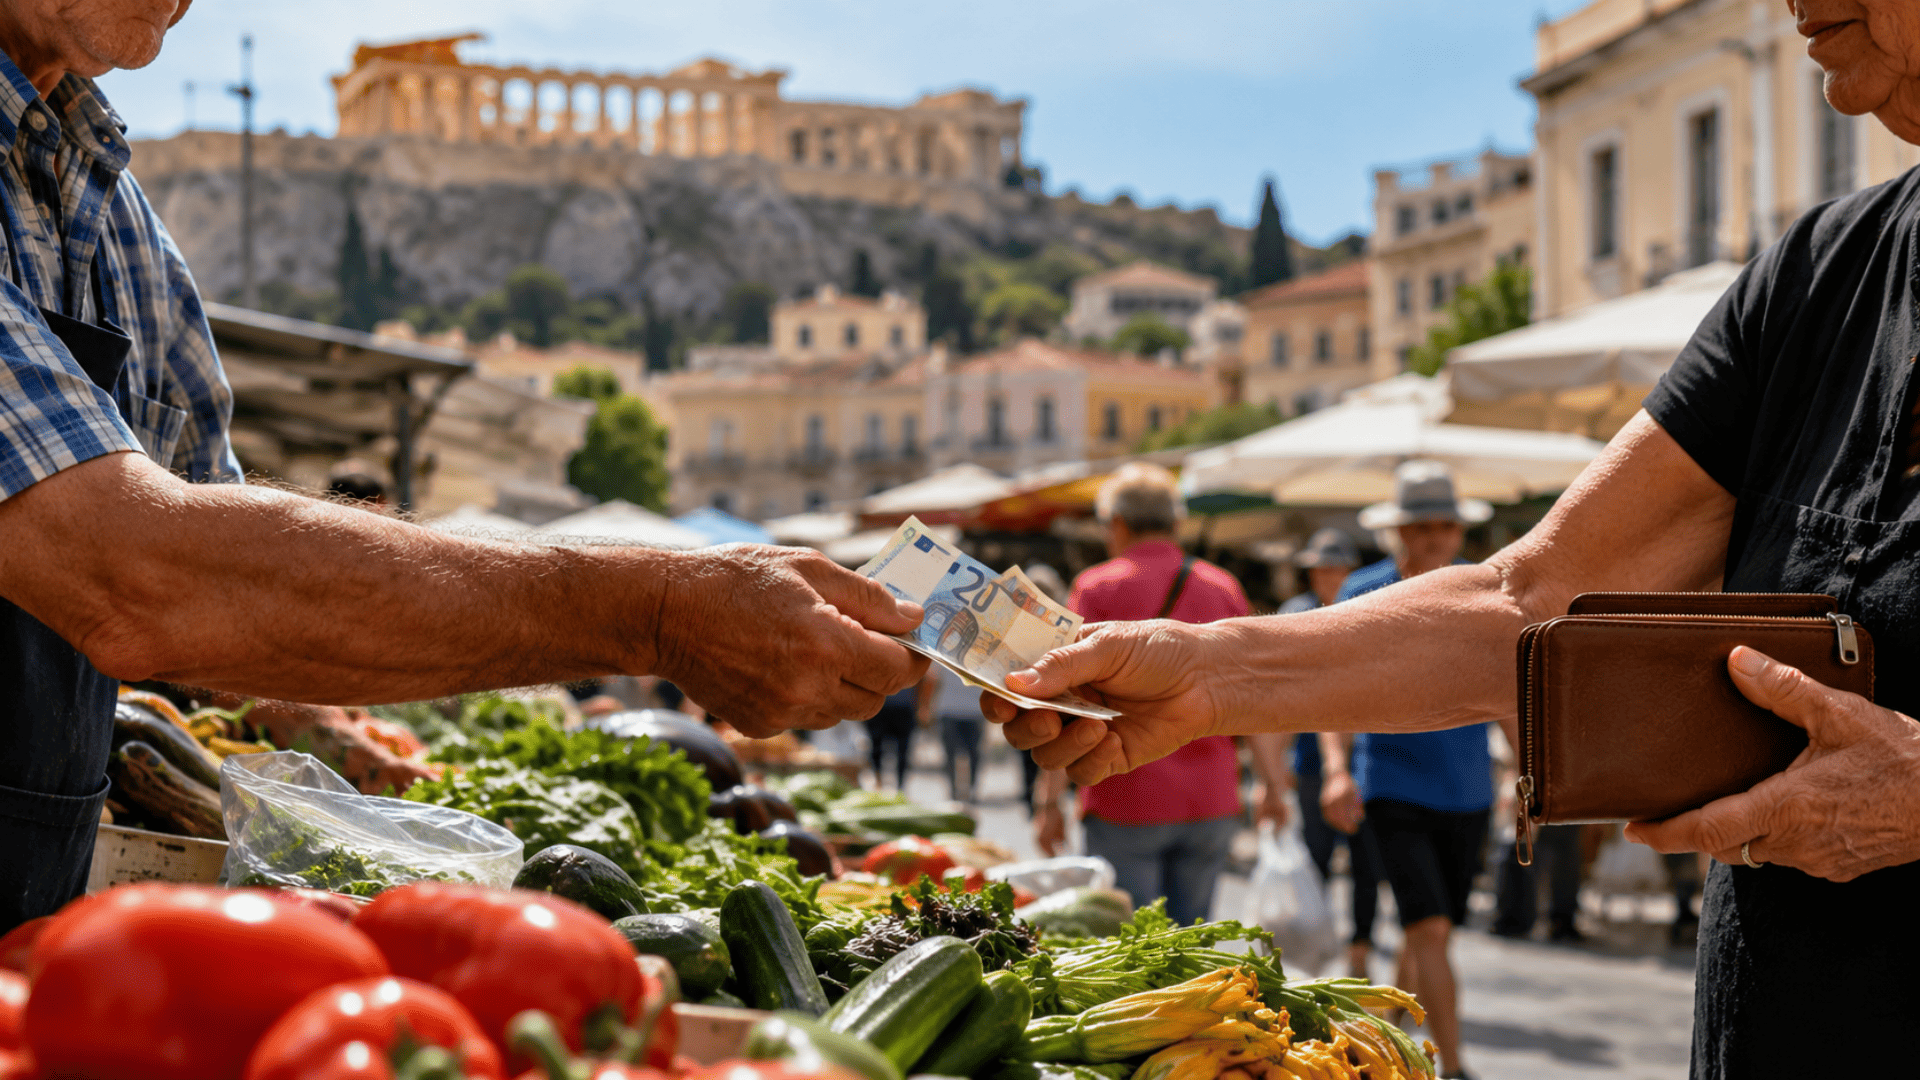
While electronic payments are becoming increasingly common across Europe, Greece still maintains a rather distinctive characteristic: cash continues to play a very significant role in daily transactions.
According to a survey by the European Central Bank (ECB) cited by Kathimerini, Greece is currently the country with the highest percentage of businesses accepting cash in the euro area.
Specifically, 99% of businesses in Greece still accept cash from customers, significantly higher than the 92% average for the entire euro area. In the restaurant, bar and café sector, the figure remains as high as 93%.
This figure shows something quite interesting: although Greece’s electronic payment system has developed rapidly, cash remains an important part of the country’s economic life.
Is Greece the country that uses cash the most in the euro area?
According to the latest ECB survey, 99% of the Greek businesses surveyed accept cash, up from the previous survey in 2024.
Meanwhile, the average for the euro area is 92%.
The differences between countries are also quite clear. Cyprus has only around 76% of businesses accepting cash, while Belgium stands at 81%.
Notably, even as digital payment methods continue to develop, a significant proportion of Greek businesses still regard cash as a stable and easy-to-use means of payment.
The survey also shows that 23% of Greek businesses said they could stop accepting cash within the next 5 years. This is the second-highest rate in the euro area, after Cyprus at 51%.
This shows that the market is positioned between two trends:
Cash remains widespread – but the transition toward electronic payments is taking place.
But Greece is not outside the wave of digital payments
The continued prevalence of cash does not mean Greece is slow to digitize.
On the contrary, data from the Bank of Greece show that card payments have increased significantly in recent years.
As of December 2025, Greece had approximately 22.9 million active payment cards, an increase of 12% compared with the same period of the previous year.
Of these:
- Debit cards reached 19.5 million, an increase of 13%.
- Credit cards reached 3.3 million, an increase of 4%.
- Prepaid cards reached 2.8 million, an increase of as much as 70%.
Throughout 2025, the total number of card transactions reached approximately 2.7 billion transactions, an increase of 10%, with a total value of approximately EUR 119.5 billion, an increase of 6% compared with 2024.
Thus, two realities are existing in parallel:
People and businesses still use cash widely, while electronic payments are also expanding at a significant pace.
A market changing its payment habits
The ECB survey shows that consumers across the euro area are increasingly inclined to use cashless payments.
In the 2024 survey, cash still accounted for 52% of point-of-sale (POS) transactions across the euro area, but this proportion had declined compared with previous years.
For Greece, one noteworthy point is that 50% of respondents said they prefer to use cash when transferring money to friends or relatives, significantly higher than in many Western European countries.
The ECB also notes that consumers generally view cash as offering advantages in terms of spending control and privacy, while cards and other electronic payment methods are generally valued for speed and convenience.
This helps explain why cash continues to hold such a strong position in Greece, even as the digital payments ecosystem develops.
Electronic payments are also becoming part of economic activity
Another notable change is the instant payments system.
The Bank of Greece has implemented instant payments, allowing certain transactions with values of up to EUR 100,000 per transaction for eligible activities at banks.
Meanwhile, according to the Bank of Greece, credit growth to the private sector reached 7.4% in May 2026, while total deposits grew by 8.1% compared with the same period. By June 2026, the credit growth rate of the economy had increased to 5.0%, while total deposits increased by 8.8%.
These data show that behind the continued habit of using cash, Greece’s financial system is continuing to digitize and expand.
What does this mean for international investors?
For a foreign investor, the story of cash may sound like a very everyday matter.
But in reality, it reflects an important characteristic of the market:
Greece is in a process of transition rather than having completely changed its traditional payment structure.
This can be seen at several levels:
Cash remains very common in daily consumption.
Cards and electronic payments are increasing rapidly.
Banks are expanding credit and deposits.
Instant payments are being implemented.
In other words, Greece is developing a financial ecosystem that combines tradition and technology.
For international investors, what matters is not whether Greece uses more or less cash, but rather the direction in which the market is developing and how the financial system can support investment, business and real estate activities.
Real estate is also part of this transformation
As the economy becomes increasingly digital, real estate transactions and related financial activities also increasingly require transparency and the ability to trace the source of funds.
For foreign investors, this is particularly important.
A high-value real estate transaction not only requires proof of financial capacity, but must also have a clear source of funds, appropriate banking documentation and complete supporting records.
This is becoming an increasingly important part of cross-border transactions and investor due diligence.
Therefore, when entering the Greek market, investors should view the banking and payment system as part of the investment infrastructure, rather than simply as a tool for facilitating everyday transactions.
Greece Golden Visa: Combining residency rights and assets
For investors seeking a residency pathway in Europe, the Greece Golden Visa is one of the notable programs.
The program allows non-EU investors to access residency rights in Greece through qualifying forms of investment under current regulations.
The important point is that the Greece Golden Visa is not only about residency rights.
Investors can also assess the investment based on:
- Asset value;
- Location;
- Rental potential;
- Housing demand;
- Infrastructure;
- Long-term growth potential.
With a market that continues to develop in banking, electronic payments, credit and real estate, choosing the right asset and preparing transparent financial documentation from the beginning has become particularly important.
Looking at the Golden Visa from a long-term investment perspective
At Casa Seguro Capital, we do not view the Golden Visa simply as a residency program.
A good investment strategy needs to be assessed across multiple layers:
The economy → financial system → real estate market → specific asset → utilization potential → residency objectives.
The fact that Greeks still widely use cash is only a small snapshot of the economy.
Behind it is a banking system with growing credit, expanding deposits and increasingly developed electronic payments.
For international investors, this is a market that is changing step by step.
And when choosing an asset in Greece, what matters is not only “How much does the asset cost?”, but also:
Where is the asset located?
What is the actual demand like?
What is its utilization potential?
How does the financial and payment infrastructure support it?
And is the investment aligned with the family’s long-term residency strategy?
Casa Seguro Capital accompanies investors throughout the process of exploring the Greece Golden Visa, selecting assets and building an investment–residency strategy aligned with long-term objectives.